
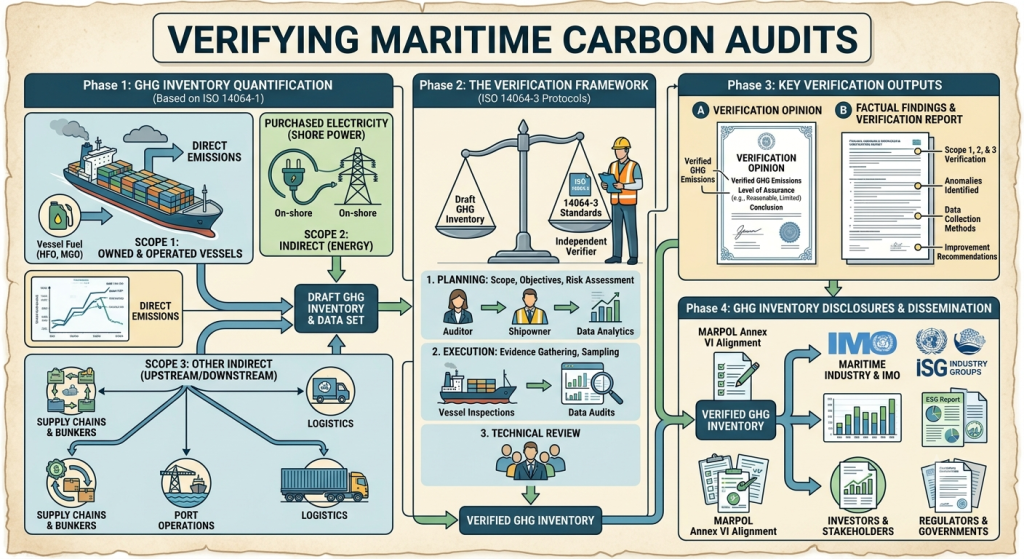
The global maritime logistics sector has entered an era of mandatory carbon accounting, where emissions metrics directly govern vessel charterability, capital access, regulatory penalties, and corporate valuations. With the enforcement of the European Union’s Corporate Sustainability Reporting Directive (CSRD) under ESRS E1, mandatory climate disclosure regimes across North America, the UK, and Australia, alongside market-based carbon pricing via the EU Emissions Trading System (EU ETS) and FuelEU Maritime, unverified or estimated carbon reporting poses unacceptable legal and financial exposure.
To satisfy institutional investors, marine underwriters, and trade regulators, maritime entities must move beyond superficial carbon estimations. Establishing an auditable Greenhouse Gas (GHG) Inventory requires strict adherence to international standards—specifically ISO 14064-1 (organizational quantification) and ISO 14064-3 (third-party verification)—complemented by financial assurance frameworks such as ISAE 3410 and the emerging ISSA 5000.
MARITIME CARBON AUDIT INTEGRATION ARCHITECTURE
┌────────────────────────────────────────────────────────────┐
│ Regulatory & Disclosure Driver Layer │
│ EU CSRD (ESRS E1) | SEC Climate Rules | EU ETS / FuelEU│
└─────────────────────────────┬──────────────────────────────┘
│
▼
┌────────────────────────────────────────────────────────────┐
│ ISO 14064-1 Organizational Footprint Layer │
│ Scope 1: Direct Fleet Fuel | Scope 2: Shore Power/Grid │
│ Scope 3: Upstream Shipbuilding, Spare Parts & Logistics │
└─────────────────────────────┬──────────────────────────────┘
│
▼
┌────────────────────────────────────────────────────────────┐
│ Third-Party Independent Assurance Layer │
│ ISO 14064-3 Verification / ISAE 3410 / ISSA 5000 │
│ Limited Assurance (2024-2026) ──► Reasonable Assurance │
└────────────────────────────────────────────────────────────┘
This whitepaper delivers an operational and legal framework for C-suite executives, chartering directors, and supply chain counsel, analyzing:
- Scope Categorization: Defining maritime operational boundaries across direct fleet combustion (Scope 1), purchased grid/shore power (Scope 2), and value chain activities (Scope 3).
- ISO 14064-1 Architecture: Establishing auditable organizational boundaries through the Operational Control vs. Equity Share approaches.
- Verification Dynamics: Navigating ISO 14064-3 audit methodologies, evaluating Materiality Thresholds, and transitioning from Limited to Reasonable Assurance.
- Automated Data Pipelines: Implementing immutable, telemetry-driven carbon accounting infrastructure to eliminate greenwashing risk.
1. Categorizing Maritime Emissions: Scope 1, Scope 2, and Scope 3 Boundaries
Accurate greenhouse gas accounting depends on establishing strict operational boundaries that prevent double-counting while ensuring complete coverage of organizational climate impacts. The maritime sector presents unique boundary challenges due to complex vessel ownership models, bareboat versus time charter arrangements, and global supply chain fragmentation.
Plaintext
┌──────────────────────────────────────────────────────────────────────────────┐
│ MARITIME GHG EMISSIONS TAXONOMY │
├──────────────┬───────────────────────────────────┬───────────────────────────┤
│ EMISSION SCOPE│ MARITIME OPERATIONAL SOURCE │ DATA RETRIEVAL SOURCE │
├──────────────┼───────────────────────────────────┼───────────────────────────┤
│ Scope 1 │ Direct vessel fuel combustion │ Mass Flow Meters, Telemetry,│
│ (Direct) │ (Main/Aux engines, boilers, incinerators) BDNs, Continuous Emissions Mgt│
├──────────────┼───────────────────────────────────┼───────────────────────────┤
│ Scope 2 │ Purchased electricity for shore │ Port Authority Metering, │
│ (Indirect) │ power (cold ironing) & port depots│ Utility Invoices, Guarantees│
├──────────────┼───────────────────────────────────┼───────────────────────────┤
│ Scope 3 │ Upstream capital goods (shipyards),│ Supplier Product Carbon │
│ (Value Chain)│ bunker fuel Well-to-Tank (WTT), │ Footprints (PCFs), IMEF │
│ │ chartered assets, freight transport│ Framework, Activity Data │
└──────────────┴───────────────────────────────────┴───────────────────────────┘
Scope 1: Direct Fleet Emissions
Scope 1 encompasses direct GHG emissions originating from sources owned or controlled by the reporting entity. In ocean shipping, Scope 1 is dominated by heavy fuel oil (HFO), very low sulfur fuel oil (VLSFO), liquefied natural gas (LNG), and alternative fuel combustion in propulsion engines, auxiliary generators, and boilers.
To achieve audit readiness, Scope 1 accounting must capture all greenhouse species mandated by the IMO and EU—carbon dioxide (), methane (
) slip from dual-fuel engines, and nitrous oxide (
)—converted into carbon dioxide equivalent (
) using IPCC Global Warming Potential (GWP) metrics.
Scope 2: Indirect Energy Emissions
Scope 2 covers indirect GHG emissions associated with the generation of purchased electricity, steam, heating, or cooling consumed by the organization. For shipowners and terminal operators, Scope 2 focuses primarily on:
- Cold Ironing (Shore Power): High-voltage onshore power supply (OPS) consumed by vessels at berth to shut down auxiliary engines.
- Terminal & Port Facility Operations: Electricity consumed by container gantry cranes, automated stacking cranes, and port administration facilities.
Under ISO 14064-1 and the GHG Protocol Scope 2 Guidance, entities must dual-report Scope 2 using both Location-Based (grid average emission factors) and Market-Based (contract-specific emission factors, Green Tariffs, or Energy Attribute Certificates) methods.
Scope 3: Value Chain Emissions
Scope 3 covers all other indirect emissions occurring across the upstream and downstream value chain. While historically excluded from mandatory corporate reporting, Scope 3 accounts for up to 80% of a cargo owner’s (BCO) total environmental footprint and represents a critical focus for CSRD ESRS E1 compliance. Within maritime logistics, key Scope 3 categories include:
- Category 1 (Purchased Goods and Services): Embodied carbon in vessel spare parts, lubricants, paint, provisions, and maritime services.
- Category 2 (Capital Goods): Embodied emissions generated during vessel shipbuilding, major drydock retrofits, and steel production.
- Category 3 (Fuel- and Energy-Related Activities Not Included in Scope 1 or 2): Upstream Well-to-Tank (WTT) emissions incurred during marine fuel extraction, refining, processing, and transportation.
- Category 6 & 7 (Business Travel & Employee Commuting): Crew rotation travel via commercial aviation and ground transport.
2. ISO 14064-1 Organizational Footprint Architecture
ISO 14064-1 provides the international specification for quantifying and reporting organizational GHG emissions and removals. Unlike project-specific standards, ISO 14064-1 establishes a systematic framework for consolidating emissions across complex corporate structures.
Plaintext
ISO 14064-1 CONSOLIDATION APPROACH SELECTION
┌─────────────────────────────────────────────────────────────────────────┐
│ Corporate Entity / Shipowner │
└─────────────────────────────────┬───────────────────────────────────────┘
│
┌────────────────────────┴────────────────────────┐
▼ ▼
┌─────────────────────────────────┐ ┌─────────────────────────────────┐
│ Control Approach │ │ Equity Share Approach │
│ Consolidates 100% of emissions │ │ Consolidates emissions based on │
│ from assets where the company │ │ the economic interest/ownership │
│ exercises Financial or │ │ percentage in the joint venture │
│ Operational Control. │ │ or vessel SPV. │
└─────────────────────────────────┘ └─────────────────────────────────┘
Operational Control vs. Equity Share Frameworks
Selecting the consolidation approach determines which vessels, subsidiaries, and joint ventures enter the corporate GHG inventory:
- Operational Control Approach: An entity accounts for 100% of GHG emissions from operations over which it has the full authority to introduce and implement operating policies. In time-chartered vessel arrangements, operational control accounting requires precise contractual evaluation: while the shipowner retains technical control of the engine room, the charterer dictates speed, route, and fuel procurement.
- Financial Control Approach: The entity reports 100% of emissions from operations where it has the ability to direct financial and operating policies to gain economic benefits.
- Equity Share Approach: Emissions are consolidated according to the entity’s economic percentage share in joint venture vessel Special Purpose Vehicles (SPVs) or co-owned fleet operations.
Quantifying Baseline Emissions and Fuel Factors
ISO 14064-1 mandates that quantification methodologies minimize uncertainty and yield accurate, reproducible results. Maritime calculations transition across three data maturity tiers:
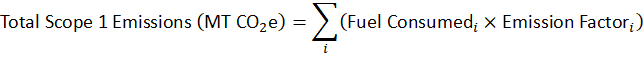
- Tier 1 (Spend-Based / Default Factor): Multiplying fuel procurement cost by standard macro-economic emission factors. Acceptable for initial Scope 3 screening but carries an uncertainty margin of 40% to 80%.
- Tier 2 (Activity-Based / Standard Factor): Utilizing measured fuel mass (from Bunker Delivery Notes) multiplied by standardized IMO/ISO carbon factors (
for VLSFO).
- Tier 3 (Direct Telemetry & Sensor Fusion): Integrating high-frequency sensor readings from mass flow meters, engine RPM monitors, and continuous emission monitoring systems (CEMS), providing audit-grade continuous data streams.
3. Third-Party Verification under ISO 14064-3 and Financial Assurance Standards
Quantifying emissions is only the first step; regulatory compliance and commercial trust require independent, third-party verification. ISO 14064-3 outlines the requirements for validating and verifying GHG assertions, providing the technical framework used by classification societies (e.g., DNV, ABS, Lloyd’s Register) and accredited sustainability auditors.
┌──────────────────────────────────────────────────────────────────────────────┐
│ GHG ASSURANCE & VERIFICATION COMPARISON MATRIX │
├──────────────────────────────┬───────────────────────┬───────────────────────┤
│ ASSURANCE ATTRIBUTE │ LIMITED ASSURANCE │ REASONABLE ASSURANCE │
├──────────────────────────────┼───────────────────────┼───────────────────────┤
│ Regulatory Expectation │ CSRD Phase-In Stage │ CSRD Target Stage │
│ │ (2024–2026 Mandate) │ (2028+ Mandate) │
├──────────────────────────────┼───────────────────────┼───────────────────────┤
│ Audit Procedure Depth │ High-level analytical │ Detailed substantive │
│ │ reviews & inquiry │ testing, site visits │
├──────────────────────────────┼───────────────────────┼───────────────────────┤
│ Verification Statement Format│ “Nothing has come to │ “In our opinion, the │
│ │ our attention to │ GHG statement is │
│ │ suggest non-compliance”| fairly stated…” │
├──────────────────────────────┼───────────────────────┼───────────────────────┤
│ Risk of Misstatement │ Moderate confidence; │ High confidence; │
│ │ higher residual risk │ minimal residual risk │
└──────────────────────────────┴───────────────────────┴───────────────────────┘
ISO 14064-3 Audit Execution Methodology
The ISO 14064-3 verification process follows a structured, evidence-based audit workflow:
- Strategic Analysis & Risk Assessment: The verifier evaluates the organization’s scale, complex chartering structures, primary emissions sources, and internal control environment to identify areas prone to material misstatement.
- Verification Plan & Sampling Protocol: Establishing sampling ratios for vessel logbooks, fuel mass flow calibration records, BDNs, and shore-side power utility bills.
- Substantive Testing & Site Visits: Executing physical onboard vessel inspections and shore-side IT system audits to verify that recorded data matches physical vessel consumption.
- Materiality Threshold Evaluation: Assessing identified errors against the predefined Materiality Threshold (typically 5% for aggregate corporate emissions inventories, or 2% to 3% for large single-point compliance programs).
Convergence with ISAE 3410 and ISSA 5000
While ISO 14064-3 serves as the primary technical standard for carbon verifiers, institutional investors and financial regulators often require assurance executed under accounting profession frameworks:
- ISAE 3410 (Assurance Engagements on Greenhouse Gas Statements): Developed by the International Auditing and Assurance Standards Board (IAASB), ISAE 3410 bridges financial reporting controls with climate data.
- ISSA 5000 (General Requirements for Sustainability Assurance): Transitioning into force as the global umbrella standard for all sustainability disclosures, unifying ISO technical approaches with financial audit rigor under CSRD and international frameworks.
4. Operationalizing an Audit-Ready Maritime GHG Data Pipeline
To transition from costly, reactive annual carbon reporting to continuous audit-readiness, enterprise maritime organizations must construct automated data architecture. Relying on manual spreadsheet aggregation exposes companies to data corruption, human error, and audit failures.
AUTOMATED AUDIT-READY DATA PIPELINE
┌──────────────────────────────┐ ┌──────────────────────────────┐
│ Asset Level Data Capture │──────►│ Data Ingestion & Invariant │
│ Telemetry, Mass Flow Meters, │ │ Validation Layer │
│ Digital BDNs, Port Power │ │ API Data Ingestion, Automated│
└──────────────────────────────┘ │ Anomaly & Outlier Detection │
└──────────────┬───────────────┘
│
▼
┌──────────────────────────────┐ ┌──────────────────────────────┐
│ Verification & Export Layer │◄──────│ Central GHG Engine │
│ Automated ISO 14064 Reports, │ │ ISO 14064-1 Logic Engine, │
│ Immutable Audit Trail Log │ │ Emission Factor Database │
└──────────────────────────────┘ └──────────────────────────────┘
Key Components of an Audit-Ready Data Pipeline
- Automated Ingestion at Source: Direct digital integration with vessel IoT telematics, fuel mass flow meters, electronic Bunker Delivery Notes (e-BDNs), and port terminal power metering, bypassing manual logbook entries.
- Automated Data Validation & Outlier Detection: Deploying rule-based algorithms that flag anomalous fuel consumption spikes, missing voyage segments, or impossible speed-and-consumption curves prior to inventory consolidation.
- Immutable Audit Trail Trail Management: Maintaining time-stamped, version-controlled records of all calculation methodologies, global warming potential (GWP) revisions, and custom emission factor selections.
- Integration with Procurement & Freight Systems: Utilizing standardized value chain calculation frameworks—such as the IMPA Maritime Environmental Footprint (IMEF) framework—to collect verified Product Carbon Footprint (PCF) data from marine suppliers for Scope 3 Category 1 tracking.
5. Regional Regulatory Disclosures across Tier-1 Jurisdictions
Global maritime operators face a patchwork of jurisdiction-specific climate disclosure mandates that leverage ISO carbon accounting principles.
┌──────────────────────────────────────────────────────────────────────────────┐
│ TIER-1 REGIONAL CLIMATE DISCLOSURE REQUIREMENTS │
├──────────────┬──────────────────┬────────────────────┬───────────────────────┤
│ JURISDICTION │ REGULATION │ IN-SCOPE ENTITIES │ ASSURANCE REQUIREMENT │
├──────────────┼──────────────────┼────────────────────┼───────────────────────┤
│ European │ CSRD / ESRS E1 │ EU & non-EU large │ Mandatory Limited │
│ Union │ │ listed/unlisted │ Assurance; moving to │
│ │ │ maritime companies │ Reasonable Assurance │
├──────────────┼──────────────────┼────────────────────┼───────────────────────┤
│ United │ SEC Climate │ US Publicly Traded │ Scope 1 & 2 Limited │
│ States │ Rules │ Registrants │ Assurance for Large │
│ │ │ (U.S. Listed) │ Accelerated Filers │
├──────────────┼──────────────────┼────────────────────┼───────────────────────┤
│ United │ SDR / CFR │ Large UK Corporates│ ISO 14064 / ISAE 3410 │
│ Kingdom │ Disclosures │ & Shipowners │ Audit Readiness │
├──────────────┼──────────────────┼────────────────────┼───────────────────────┤
│ Australia │ Mandatory Climate│ Large Australian │ Phased Assurance │
│ │ Reporting (AASB) │ Entities & Ports │ Roadmap (Scope 1–3) │
└──────────────┴──────────────────┴────────────────────┴───────────────────────┘
European Union (CSRD & FuelEU Maritime)
Under ESRS E1, companies in scope of the CSRD must disclose complete Scope 1, 2, and material Scope 3 emissions using audit-ready metrics. This data must undergo mandatory third-party limited assurance, transitioning toward reasonable assurance. Concurrently, compliance with FuelEU Maritime requires ship-specific well-to-wake GHG intensity verification by accredited verifiers.
United States (SEC & State Level Requirements)
The SEC Climate Disclosure Rules mandate large accelerated filers to disclose material Scope 1 and Scope 2 emissions, supported by independent assurance reports. Additionally, state-level legislation (such as California’s Climate Corporate Data Accountability Act) requires large corporations doing business in the state to disclose Scope 1, 2, and 3 emissions evaluated under GHG Protocol and ISO standards.
United Kingdom and Australia
The UK’s Sustainability Disclosure Requirements (SDR) and Australia’s mandatory climate disclosure framework align closely with the International Sustainability Standards Board (ISSB) S2 climate-related disclosures. Both jurisdictions mandate structured reporting of Scope 1 and 2 emissions, alongside material Scope 3 value chain impacts, reinforcing global convergence toward ISO 14064-3 verification standards.
Conclusion: Strategic 3-to-5-Year Horizon
Over the next 3 to 5 years, unverified carbon accounting will carry severe commercial and legal penalties. Shipowners and freight logistics providers operating with estimated or unverified data will face higher capital costs from banks adhering to the Poseidon Principles, higher insurance premiums, commercial exclusion from long-term green charter agreements, and potential regulatory fines under EU ETS and CSRD regimes.
MARITIME CARBON ACCOUNTING MATURITY CURVE
Phase 1: Reactive Estimation ► Phase 2: ISO 14064 Verification ► Phase 3: Continuous Audit Readiness
• Manual Spreadsheets • Periodic Third-Party Audit • Automated IoT Telemetry
• Spend-based Scope 3 • Limited Assurance Statement • Real-time Scope 1-3 Engine
• High Uncertainty Margin • CSRD Baseline Compliance • Reasonable Assurance Ready
By investing in continuous, sensor-driven data ingestion, establishing clear operational control boundaries under ISO 14064-1, and subjecting GHG inventories to independent verification under ISO 14064-3 and ISAE 3410 / ISSA 5000, enterprise maritime organizations protect their commercial viability and establish market leadership in the decarbonized trade economy.
Deep-Dive Frequently Asked Questions (FAQs)
Q1: What is the primary difference between using the GHG Protocol Corporate Standard and ISO 14064-1 for maritime carbon accounting?
Answer: The GHG Protocol Corporate Standard and ISO 14064-1 are highly complementary and fully compatible frameworks. The GHG Protocol provides detailed, practical guidance on accounting methodologies, emissions factors, and categorization rules across Scopes 1, 2, and 3.
ISO 14064-1, however, is an international standard that defines formal organizational requirements for quantifying, documenting, managing data quality, and preparing a GHG inventory for formal third-party audit. Most leading maritime enterprises use the GHG Protocol to structure their calculation rules and Scope 3 categories, while utilizing ISO 14064-1 to structure their overall management system and verification trail to ensure regulatory compliance.
Q2: How do time charter parties affect operational control boundaries under ISO 14064-1?
Answer: Under the Operational Control Approach of ISO 14064-1, an entity reports 100% of emissions from operations where it has the authority to introduce and implement operating policies. In a time charter party, the shipowner maintains technical control (engine maintenance, crewing, safety), while the charterer exercises commercial control (speed, route selection, port calls, and fuel purchasing).
For CSRD and regulatory reporting, if the charterer dictates fuel procurement and speed, they often account for the vessel’s voyage emissions under their operational control or Scope 3 Category 3/4 reporting. Conversely, if the shipowner reports under strict vessel asset ownership guidelines, they consolidate Scope 1 emissions while disclosing charterer usage parameters. Defining these boundaries clearly in charter party agreements is critical to preventing double-counting or regulatory reporting gaps.
Q3: What is the operational distinction between Limited Assurance and Reasonable Assurance under ISO 14064-3?
Answer: The distinction lies in the depth of audit testing performed and the resulting level of confidence expressed in the verification statement:
- Limited Assurance: The verifier performs analytical procedures, high-level inquiries, and sampling to confirm that no material errors are evident. The resulting audit statement is expressed negatively (“Nothing has come to our attention to indicate that the report is materially misstated”).
- Reasonable Assurance: The verifier conducts extensive substantive testing, detailed trace-back of source telemetry data, calibration checks of onboard meters, physical vessel site visits, and internal control reviews. The statement is expressed positively (“In our opinion, the GHG inventory is fairly stated in all material respects”). CSRD mandates a transition from Limited to Reasonable Assurance over time.
Q4: Why is activity-based data required to replace spend-based data for Scope 3 Category 1 (Purchased Goods) accounting?
Answer: Spend-based data relies on multiplying procurement expenditures by broad macro-economic industry emission factors. While acceptable for high-level screening, spend-based estimates carry high uncertainty (40% to 80%), fluctuate with currency inflation, and fail to reflect actual decarbonization efforts by suppliers.
Activity-based data utilizes physical quantities (e.g., metric tons of steel, liters of lubricant, exact supplier energy consumption) multiplied by specific Product Carbon Footprints (PCFs). Transitioning to activity-based data allows shipowners to capture tangible emissions reductions when procurement teams select lower-carbon suppliers or retrofitted spare parts.
Q5: How do ISAE 3410 and ISSA 5000 relate to ISO 14064-3 in corporate carbon audits?
Answer: ISO 14064-3 is a technical verification standard created specifically for environmental and technical carbon verifiers. ISAE 3410 (and the overarching ISSA 5000 framework) was created by the international accounting standards board for financial auditors to verify greenhouse gas statements integrated into corporate financial reports.
In modern ESG audits, accredited verifiers often perform dual-aligned audits—using ISO 14064-3 technical methodologies to evaluate physical fuel data and sensor telemetry, while applying ISAE 3410 / ISSA 5000 procedures to assure internal financial controls and risk management systems for public corporate disclosures.
For technical inquiries regarding GHG inventory auditing, ISO 14064 compliance mapping, or automated carbon accounting pipeline deployment, contact Oitha Marine’s Regulatory Compliance & Sustainability Advisory.
Recent Comments